
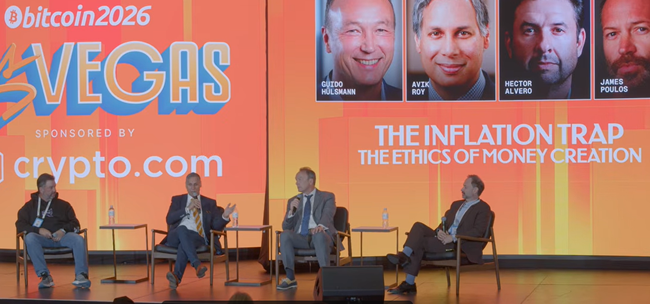
This note forms part of my preparation for possible responses to questions and objections concerning my paper “Beyond Gold: Bitcoin and the Digital Reconfiguration of Sound Money”, which I will present at the 10th Annual Madrid Conference on Austrian Economics in October 2026. In that context, I take very seriously Professor Hülsmann’s recent warning about Bitcoin and fractional-reserve practices, made at a recent Bitcoin conference held in Las Vegas.[1]
Bitcoin is not automatically immune to the institutional developments that historically transformed monetary systems based on sound money. Custodians may emerge. Exchanges may operate on a fractional-reserve basis. Financial institutions may issue more claims to bitcoin than the bitcoins they actually hold. None of this is prevented by the mere existence of the Bitcoin protocol.
Hülsmann and the Real Problem of Fractional-Reserve Banking
Hülsmann’s earlier analyses of fractional-reserve banking help, in my view, to identify the problem more precisely.[2] The crucial question is not simply whether claims to money can exist. Nor is it, by itself, merely the existence of claims that are not fully backed. The deeper monetary problem arises when fractional-reserve claims become sufficiently homogeneous, standardized, and widely accepted that market participants begin to treat them as equivalent to money itself, or as equivalent to fully backed money substitutes.
This distinction is fundamental. A fully backed money substitute does not create an additional quantity of the underlying monetary asset. It represents an existing monetary unit. A fiduciary medium, by contrast, is a claim that functions as a money substitute despite not being backed by the underlying money.
Under the historical gold standard, this difference could be particularly difficult for the ordinary monetary user to observe. A banknote fully backed by gold and an otherwise identical banknote issued without the corresponding reserves could circulate in exactly the same way. The person accepting the banknote could not determine, from the note itself, whether the issuing institution actually held the gold required for redemption.
This is one of the points emphasized by Mises. Money certificates and fiduciary media could be physically and functionally indistinguishable in everyday exchange. Once bank liabilities became sufficiently homogeneous and were accepted at par, the market distinction between one type of claim and another could disappear from ordinary monetary practice.
Hülsmann’s analysis is especially useful here. If the promissory notes or claims issued by fractional-reserve institutions remain heterogeneous, if each issuer carries its own identifiable risk, and if market participants recognize that they are dealing with the liability of a particular institution, those claims need not become widely accepted money substitutes. And their failure primarily affects those who voluntarily accepted them.
The systemic monetary problem becomes much more serious when those heterogeneous liabilities become homogenized. When claims issued by different institutions become standardized, interchangeable, and accepted at par, the identity and solvency of the particular issuer become less visible to the user. What was previously a particular credit instrument may increasingly begin to function as a widely accepted money substitute.
From Gold to Bitcoin: Money and Claims to Money
And this is where, in my view, the comparison with Bitcoin becomes particularly interesting.
Bitcoin does not prevent fractional-reserve practices. An exchange may tell ten customers that each of them owns one bitcoin while in reality holding only five bitcoins. In that case, the exchange will have created ten claims to bitcoin backed by only five actual bitcoins. But those claims are not bitcoin. They are liabilities of that particular exchange.
This distinction may remain economically relevant in a much more transparent way than in the classical case of standardized banknotes. If a customer wishes to withdraw bitcoin into self-custody, the exchange must deliver actual bitcoin. If a payment must be settled with a party outside the exchange that requires bitcoin, actual bitcoin must be delivered. If another institution requires final settlement rather than accepting the exchange’s internal accounting entry, the intermediary must again provide actual bitcoin. The intermediary can inflate its liabilities, but it cannot inflate Bitcoin.
This does not mean that fractional-reserve practices are harmless. They can generate counterparty risk, insolvency, financial contagion, price distortions, and very substantial losses for customers. But the distinction between the underlying monetary asset and the claims issued against it remains conceptually clear.
Scaling Bitcoin Without Fiduciary Media
Bitcoin also adds another important element: users do not necessarily have to accept such claims.
Bitcoin can be held directly in self-custody. More importantly, scaling the use of Bitcoin beyond the base layer does not necessarily require the creation of fiduciary media. This point deserves particular emphasis because it marks an important difference from the historical development of gold.
The physical characteristics of gold encouraged the emergence of custody, certificates, bank deposits, clearing systems, and money substitutes. Transporting and safeguarding gold was costly. For that reason, large-scale monetary use generated strong incentives to economize on the direct movement of the monetary asset itself.
Bitcoin faces a different scalability problem, but its solution does not necessarily require unbacked claims. Second-layer systems such as the Lightning Network, in which the user does not need to hand custody of his bitcoins to an intermediary, illustrate this general possibility. Lightning is not a classical example of a money substitute; at most, it might be regarded as a sui generis solution. But what matters here is not so much its exact conceptual classification as its function. With Lightning, Bitcoin can be used beyond ordinary base-layer transactions without requiring an institution to issue unbacked redeemable claims to bitcoin.
Likewise, systems in which custody is entrusted to a third party could, in principle, operate with full backing, and technological mechanisms could make the existence of reserves more transparent or verifiable than in traditional banking systems.
This means that the choice is not limited to using Bitcoin directly on Layer 1 or relying on fractional-reserve intermediaries. There is a third possibility: scaling monetary use while maintaining full backing or using mechanisms that do not require entrusting custody of the bitcoins to an intermediary.
Can “Paper Bitcoins” Neutralize the 21 Million Limit?
A further issue of great importance for Bitcoin follows from all of the above. The 21 million constraint does not, by itself, prevent an expansion in the supply of media denominated in bitcoin. The protocol can enforce a fixed supply of bitcoin while financial institutions create additional claims to bitcoin.
As long as those claims to bitcoin remain heterogeneous and are recognized as liabilities of particular issuers, the distinction remains clear. But let us imagine a different development.
Suppose that banks, exchanges, payment providers, or other financial institutions begin issuing standardized claims denominated in bitcoin. Suppose that those claims become interoperable across institutions. Suppose that they are routinely accepted at par with actual bitcoin. And suppose that users gradually stop demanding settlement in the underlying asset because those claims are used in everyday transactions as perfect substitutes for bitcoin.
At that point, the nature of the problem changes. The protocol could continue to enforce exactly the same supply rule. Not a single additional bitcoin would need to be created. And yet the effective supply of monetary media denominated in bitcoin could have expanded considerably.
If one bitcoin serves as backing for several claims that are all used as if they represented immediately available bitcoin, the monetary consequences of scarcity at the base layer would be partially diluted.
In this sense, the most important indirect threat to Bitcoin’s monetary scarcity would not necessarily be a violation of the 21 million rule. It would be the creation and monetary adoption of fiduciary claims on top of that fixed base.
The threat would not necessarily be to Bitcoin’s fixed supply itself, but to the monetary effectiveness of that fixed supply. This distinction is essential. The Bitcoin protocol could continue to function perfectly. Nodes could continue rejecting any block that violated the issuance rules. The total quantity of bitcoin recognized by the network could remain unchanged. And yet an institutional superstructure could emerge in which economic actors routinely used claims to bitcoin instead of bitcoin itself.
If those claims were fully backed, no analogous monetary expansion would occur. The problem arises when unbacked claims become standardized, interoperable, and accepted at par with actual bitcoin. In other words, the critical transition does not occur when the first exchange begins operating on a fractional-reserve basis. It occurs when the market ceases to care about distinguishing which claims are backed and which are not.
Homogenization as the Real Critical Point
This is why Hülsmann’s emphasis on the homogenization of bank liabilities is so relevant to Bitcoin.
As long as a balance at Exchange A is understood as a liability of Exchange A, a balance at Exchange B as a liability of Exchange B, and actual bitcoin as something categorically different from both, the heterogeneity of those claims remains visible.
If, by contrast, a particular institutional framework turns all those balances into instruments that are interchangeable at par and allows them to circulate independently of regular settlement in bitcoin, then “paper bitcoin” begins to acquire genuine monetary significance.
That is, in my view, the scenario to which Bitcoin users should pay particular attention.
The danger would be even greater if governments, regulated banks, major exchanges, and payment institutions promoted a common standard for such claims. A standardized and interoperable system could eliminate much of the market discipline that comes from distinguishing among different issuers.
This would not necessarily imply a formal conspiracy, or even a deliberate attempt to weaken Bitcoin. There are obvious commercial incentives for financial institutions to reduce settlement costs, increase liquidity, centralize custody, and economize on reserves.
But the monetary consequence could be the same. Liabilities issued against bitcoin could gradually become substitutes for bitcoin itself.
For this reason, the existence of the 21 million limit does not, by itself, provide a sufficient guarantee of monetary soundness. The underlying asset may remain perfectly scarce and resistant to manipulation while the monetary system built upon it allows an expansion of the unbacked monetary media circulating on that base.
Bitcoin Is Not the Monetary System Built on Bitcoin
And here we return to a distinction that is central to the paper I will defend at the 10th Madrid Conference on Austrian Economics: the monetary good is not the same thing as the monetary regime built upon it.
Gold did not cease to be scarce because banks issued money substitutes, some backed and others unbacked. What changed was the monetary system built upon gold: the gold standard.
The same distinction must be applied to Bitcoin.
Bitcoin can remain perfectly scarce at the protocol level while the institutional system built around it introduces money substitutes, fiduciary media, leverage, and credit expansion.
This distinction also allows us to specify more precisely how far the danger of “paper bitcoins” extends. If a regime were to emerge in which unbacked claims to bitcoin circulated widely and were treated as equivalent to bitcoin itself, the scarcity of the underlying asset would not have disappeared. The 21 million limit would remain intact. What would have failed would be the monetary regime built on Bitcoin in its ability to transmit that scarcity to the broader set of monetary media used by economic actors.
In that sense, the expansion of unbacked money substitutes could produce effects in monetary practice similar to an expansion in the quantity of bitcoin available for exchange, even though not a single additional bitcoin had been created by the protocol. That would be precisely the risk: that the soundness of the monetary asset would cease to translate fully into the soundness of the monetary system built upon it.
The Decisive Difference with Gold
There is, however, an important difference between the two cases. Unlike gold, Bitcoin does not require this development in order to scale. Fully backed solutions, or solutions that allow users to retain direct control over their bitcoins, can perform many of the functions for which the historical use of gold ultimately came to depend on money substitutes. Users can retain direct access to the monetary asset. They can demand settlement. They can leave systems in which custody depends on a third party. And the difference between owning bitcoin and holding a claim against an intermediary can remain visible.
Bitcoin therefore does not eliminate the possibility of fiduciary media. What it does is alter the institutional conditions under which those fiduciary media can come to dominate. The danger is not the mere existence of intermediaries. Nor is it, by itself, the isolated existence of fractional-reserve institutions. The danger is the homogenization and monetary adoption of their liabilities.
If claims to bitcoin become standardized, interoperable, accepted at par, and routinely used without settlement in actual bitcoin, then Bitcoin’s fixed supply could be partially neutralized in monetary practice without any change whatsoever to the Bitcoin protocol.
By contrast, if users continue to distinguish between bitcoin, backed claims, and unbacked liabilities — and if scaling mechanisms allow them to avoid fiduciary media altogether — Bitcoin could prove considerably more resistant to the process that historically weakened the monetary discipline imposed by gold.
That is, in my view, the question that deserves our full attention. The future soundness of Bitcoin may depend not only on defending the 21 million limit, but also on preserving the distinction between bitcoin and claims to bitcoin.
NOTES
[1] Hülsmann, J. G., intervention in The Inflation Trap: The Ethics of Money Creation, Bitcoin 2026, Las Vegas. Available at: https://youtu.be/Tk0qvw_HHpc?si=jugwQJY62zFm34K1
[2] See Hülsmann, J. G. (1996), “Free Banking and the Free Bankers”, The Review of Austrian Economics, vol. 9, no. 1, pp. 3–53; and Hülsmann, J. G. (2003), “Has Fractional-Reserve Banking Really Passed the Market Test?”, The Independent Review, vol. 7, no. 3, pp. 399–422. See also a synthesis of both articles in Serrano, Joel (2025), Bitcoin as Sound Money: An Interpretation of Bitcoin in Light of the Austrian School of Economics, sections 3 and 6 of the Appendix, doctoral dissertation, Rey Juan Carlos University, Madrid. Available at: https://hdl.handle.net/10115/128557
Do you like what you are reading? Subscribe to receive updates.
Unsubscribe anytime